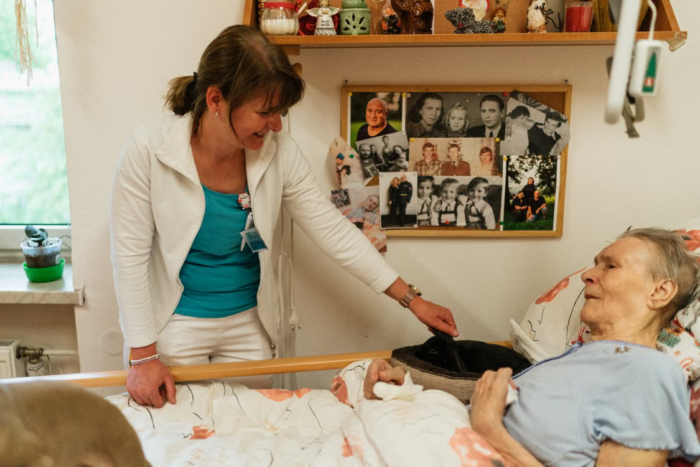
Caring for aging parents often costs far more than just the medical bills that families expect. Grocery runs, missed work, home repairs, travel, paperwork, and personal health expenses can quietly drain budgets.
Many adult children step into the role gradually. So, they may not even recognize the financial pattern until their savings begin shrinking.
Understanding the less-obvious costs can help families set boundaries, protect their long-term plans, and prepare for care needs before a crisis limits their choices.
Small Spending Can Become a Second Household Budget
Small purchases rarely feel dangerous on their own. A prescription co-pay, restaurant meal after an appointment, or tank of gas may seem manageable. But repeated expenses can quickly create a second household budget over time.
Adult children may also begin covering groceries, utility bills, medical supplies, or even property taxes without creating a formal record.
Families facing these expenses should track every payment, even when reimbursement is not expected. Because accurate records reveal how much support is truly affordable.
Reduced Work Hours Can Lower Earnings
Caregiving schedules rarely fit neatly around a full-time job. Medical appointments happen during business hours, emergencies interrupt meetings, and recovery periods can require days or weeks of hands-on help.
Reduced hours create an immediate loss of income, but the larger effects may remain hidden for years. For example, caregivers could miss promotions, employer retirement contributions, bonuses, professional training, and future raises tied to career advancement.
A lifespan-based approach can help families look beyond the next bill and consider how current decisions may affect future financial security.
Personalized, lifespan-based financial solutions, such as those available from Abacus Global Management group, can help individuals be financially prepared for their remaining years.
When a parent’s care period has no predictable end date, such financial preparation is important.
And for adult children caring for their parents, quitting a job may appear less expensive than hiring help. But paid leave, flexible scheduling, remote work, or shared family coverage may preserve more wealth than leaving the workforce completely.
Savings Withdrawals Can Create Long-Term Damage
Caregivers often turn to savings because the money is accessible and the need feels urgent. Emergency funds, education accounts, and retirement plans can quickly become sources of cash when a parent needs immediate help.
Research from Caregiving in the US found that 31% of family caregivers stopped saving, 24% used up short-term savings, and 13% tapped long-term savings. Those withdrawals can mean less protection from their own emergencies and fewer years for investments to recover.
Taxes and early-withdrawal penalties can make retirement-account withdrawals even more expensive. Lost compound growth also means a caregiver may need to work longer, save more aggressively later, or accept a lower standard of living in retirement.
Insurance Gaps Can Produce Unexpected Bills
Many families assume Medicare will cover most services that an aging parent needs. Coverage can help with qualifying hospital care, physician services, prescriptions, and limited skilled care, but it generally does not pay for ongoing custodial support.
Help with bathing, dressing, meal preparation, and other daily tasks may be necessary even when a parent does not need constant medical treatment. Families can then face private-pay costs for home-care workers, adult day programs, assisted living, or long-term nursing.
Most long-term care is not covered by Medicare or Medigap. Adult children should review a parent’s policies, income, assets, veterans’ benefits, and potential Medicaid eligibility before assuming they must personally cover every bill.
Home Safety Changes Can Cost More Than Expected
Aging in place may sound like the affordable alternative to assisted living, but an older home can require significant changes. Grab bars and brighter lighting are relatively inexpensive, while stair lifts, ramps, wider doorways, and accessible bathrooms can demand a much larger budget.
Routine maintenance may also shift to adult children when a parent can no longer handle repairs or yard work. Paying contractors for cleaning, snow removal, lawn care, plumbing, and appliance replacement can turn a mortgage-free home into an expensive place to maintain.
Families should compare renovation costs with the home’s long-term suitability. Spending heavily on modifications may offer limited value if the property remains isolated, difficult to navigate, or far from medical services.
Long-Distance Care Can Add Costs
Living far from a parent creates a financial challenge that families may overlook during early planning. Airfare, hotels, rental cars, meals, and unpaid time away from work can make each emergency visit surprisingly expensive.
Long-distance caregivers may also pay local professionals to complete tasks they cannot manage in person. Care managers, transportation services, cleaners, meal providers, and home-maintenance workers may become essential parts of the care plan.
Last-minute travel usually costs more than scheduled visits, especially during holidays or severe weather. A dedicated travel fund can help adult children respond without relying on credit cards or disrupting money reserved for their own household needs.
Family Conflicts Can Lead to Unequal Spending
Siblings do not always agree about what care a parent needs or who should pay for it. One person may contribute time, another may provide money, and a third may remain largely uninvolved, creating resentment and rushed financial decisions.
Unclear arrangements can also lead to duplicate purchases, missed bills, informal loans, and disagreements about a parent’s assets.
Written records and regular family discussions can reduce confusion while protecting the caregiver who handles most of the day-to-day responsibilities.
Legal documents deserve attention before cognitive decline or a medical emergency complicates decision-making. A durable power of attorney, health care directive, updated will, and organized account information can prevent costly delays.
Caregiver Health Can Become Another Expense
Caregivers frequently postpone their own medical appointments because a parent’s needs feel more urgent. Stress, poor sleep, skipped exercise, and rushed meals can eventually contribute to higher health care costs and additional time away from work.
Respite care may appear optional, but regular breaks can help caregivers remain healthy enough to continue providing support. Counseling, preventive care, exercise, and reliable backup help belong in the caregiving budget rather than being treated as luxuries.
Financial boundaries also protect emotional health. A sustainable plan should define what the caregiver can contribute without sacrificing housing stability, retirement security, or essential care for other family members.
Protecting Your Future While Supporting Your Parents
Caring for aging parents involves more than paying visible medical expenses. Lost earnings, depleted savings, uncovered long-term care, travel, home modifications, family disputes, and caregiver health costs can all shape a family’s financial future.
Early conversations give everyone more time to review resources, divide responsibilities, and set realistic limits.
Hopefully this article has been helpful. If so, be sure to explore some of our other insightful content.
Leave a Reply